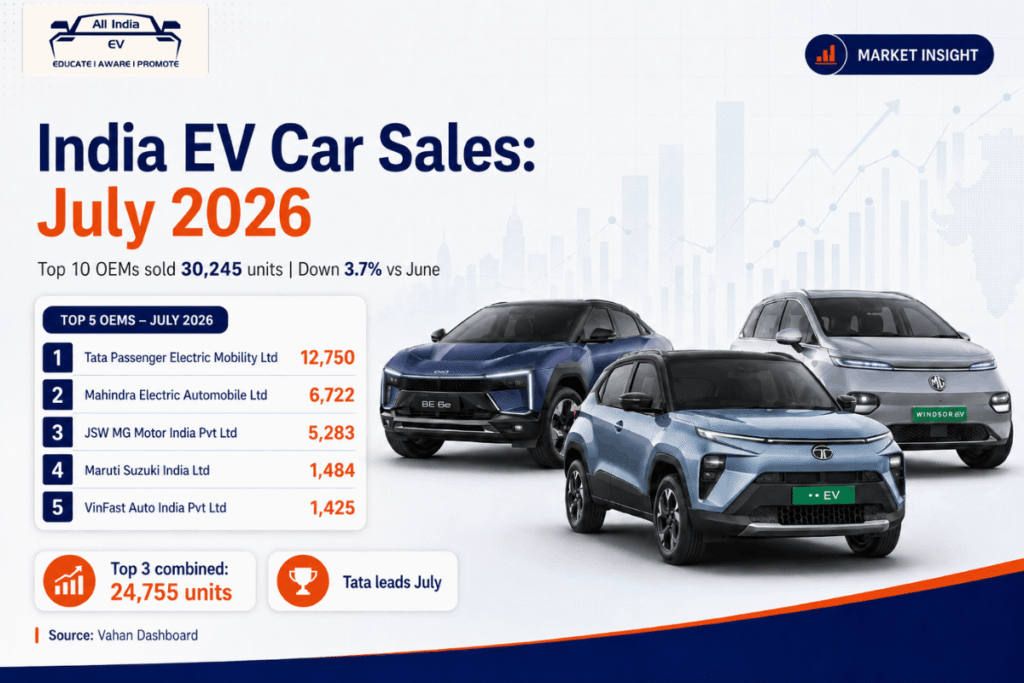

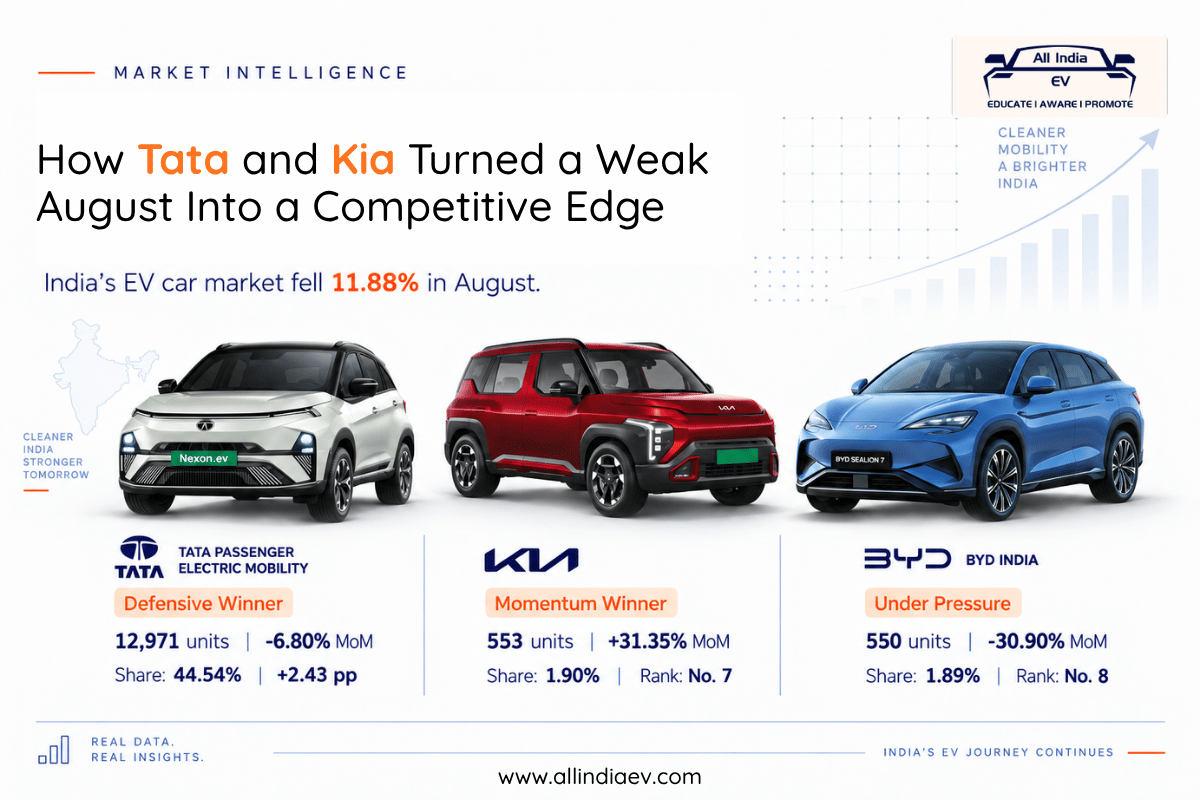
Electric car registrations in India had a rough August. Nationwide EV registrations slid from 33,050 units in July to 29,125 in August, a fall of nearly 12% in a single month. On the surface, that reads like bad news across the board. But look past the headline number, and a far more interesting story emerges: three of the country’s most closely watched EV makers moved in three completely different directions, and the reasons why matter more than the numbers themselves.
Tata Passenger Electric Mobility sold fewer cars, yet came out of August stronger than it went in. Kia, still a minor player by volume, grew faster than any of its larger rivals. BYD India, by contrast, lost nearly a third of its business in a month, and with it, a chunk of its market standing.
The lesson for anyone tracking this sector is simple but easy to forget: in a contracting market, raw sales figures can mislead. What actually separates winners from laggards is relative performance, how a company’s trajectory compares with the market around it.
Electric Car Registrations India: The Numbers, Side by Side
| Metric | Tata | Kia | BYD |
|---|---|---|---|
| July registrations | 13,917 | 421 | 796 |
| August registrations | 12,971 | 553 | 550 |
| Month-on-month change | -6.80% | +31.35% | -30.90% |
| July market share | 42.11% | 1.27% | 2.41% |
| August market share | 44.54% | 1.90% | 1.89% |
| Share movement | +2.43 pp | +0.63 pp | -0.52 pp |
| Rank movement | No. 1 → No. 1 | No. 9 → No. 7 | No. 6 → No. 8 |
The real story isn’t that one company grew and two shrank. It’s that Tata and Kia both came out ahead through entirely different routes, while BYD fell behind not just the market, but its own recent history.
Tata: Losing Volume, Gaining Ground
Tata’s headline number looks unremarkable at best: registrations fell from 13,917 to 12,971, a 6.8% drop. But set against a market that contracted by almost 12%, that decline looks like restraint rather than weakness. Tata shed volume nearly five percentage points more slowly than the industry as a whole, and that gap translated directly into share. Its slice of the national market rose from 42.11% to 44.54% in a single month.
In other words, Tata took a bigger bite out of a smaller pie.
The reason this is repeatable rather than lucky comes down to geography. Of the 23 states and union territories that recorded at least 100 EV registrations in August, Tata led in 22 of them. Its only loss was Chandigarh, where Mahindra Electric Automobile narrowly edged it out, 105 units to 103.
That kind of national footprint is not something a rival can chip away at with a single strong region or a promotional push. Tata’s advantage rests on a wide dealer and service network, a presence across multiple price points, dominance in India’s largest EV markets, and enough reach to still register meaningful volumes in smaller, emerging ones. For investors, August should be read not as a 6.8% sales decline, but as a consolidation of market power during an industry-wide correction. The open question is how long that share gain can keep offsetting weak absolute demand.
Kia: A Small Player Growing Against the Grain
Kia’s August told the opposite story. Registrations climbed from 421 to 553 units, up 31.35%, while its market share moved from 1.27% to 1.90% and its national ranking improved from roughly ninth to seventh.
An increase of 132 cars barely registers next to Tata’s tens of thousands. But context changes the picture: Kia grew while the overall market shrank by nearly 12%. That’s not a company riding a rising tide; it’s one gaining ground against the current, which is a much harder thing to do.
Encouragingly, the growth wasn’t concentrated in one lucky state. Kerala registrations more than doubled, from 28 to 57. Haryana jumped from 3 to 24. Gains showed up across several established EV markets rather than in a single outlier. That breadth matters for a challenger brand: growth built on one region can evaporate the moment a fleet order or local promotion ends, while broader gains suggest something more durable is underway.
Kia still accounts for under 2% of India’s EV registrations, so it would be premature to call it a serious threat to the market leaders. But it has earned a spot on the watchlist. The question now is whether August was a one-off spike or the start of a genuine climb toward mid-tier relevance.
BYD: When Momentum Reverses Fast
BYD’s August was the sharpest reversal of the three. Registrations fell from 796 to 550 units, a sharp 30.9% decline, roughly three times the rate at which the overall market contracted. Its national share slid from 2.41% to 1.89%, and its ranking dropped from around sixth to eighth.
The comparison with Kia is the most telling detail. In July, BYD’s 796 registrations were nearly double Kia’s 421, a comfortable lead. By August, Kia’s 553 had edged past BYD’s 550. A gap that size closing in a single month is not a rounding error; it’s a real shift in competitive standing.
The weakness wasn’t isolated to one market. Maharashtra registrations nearly halved, from 176 to 94. Delhi fell from 93 to 38. Kerala dropped from 51 to 19, and Karnataka from 38 to 13. Chandigarh was a rare bright spot, rising from 18 to 31, but the broader pattern across BYD’s key urban markets was clearly negative.
This matters more for BYD than it might for a mass-market brand, because BYD’s lineup skews toward higher price segments, a narrower buyer pool to begin with. When that pool contracts across several major cities simultaneously, the effect on national volume is outsized. One weak month doesn’t confirm a long-term decline, but it does raise a clear question worth tracking: can BYD recover its 2%-plus share, or does August mark the start of a slide?
A Simple Framework: Volume Isn’t the Whole Story
Put side by side, these three companies make the case against judging EV makers on unit sales alone.
Tata: volume down, share up. It lost registrations but grew stronger competitively, simply by declining more slowly than the market around it.
Kia: volume up, share up. The cleanest win of the three: real growth, in absolute terms, during a month when the industry was shrinking.
BYD: volume down, share down. Its decline can’t be blamed on the market alone; it lost ground on both fronts at once.
That gives a useful lens for reading any weak month in this sector:
| Position | Volume | Share | What it signals |
|---|---|---|---|
| Defensive winner | Down | Up | Outperforming a weak market |
| Momentum winner | Up | Up | Capturing incremental demand |
| Under pressure | Down | Down | Losing ground faster than the market itself |
By that measure, August had a clean split: Tata was the defensive winner, Kia was the momentum winner, and BYD faced competitive pressure.
The Takeaway
Total electric car registrations in India dropped in August, but the manufacturer-level data is a reminder of how quickly competitive positioning can shift beneath a single industry-wide number. Tata remains in a category of its own, commanding nearly 45% of the market, and its geographic spread makes that lead unusually resilient to weakness in any one state. Kia, working from a much smaller base, put up a growth number, 31.35%, against a market that fell 11.88%, that’s hard to dismiss as noise. Whether it can sustain that pace is the real test ahead. BYD’s 30.9% drop sits at the other end of the spectrum: still a meaningful player in the premium EV space, but its August performance suggests something beyond the broader slowdown was at work.
The broader point for anyone watching this market is not to ask which company sold more cars last month. It’s to ask who captured a larger share of a shrinking market, where that share came from, and whether the underlying growth is broad enough to last. August offered three very different answers to that question: Tata defended its lead, Kia built momentum, and BYD lost ground, and that divergence may end up telling investors more than the industry’s headline decline ever could.